⚡ Quick Answer
The YNAB student discount isn’t a discount at all. It’s a completely free 365-day subscription worth $109, open to any currently enrolled college student, verified through SheerID at ynab.com/college. No credit card, no reduced features, no percentage-off code to search for.
How We Review Apps · Pricing verified from ynab.com — September 5, 2026
📋 Table of Contents
- Is the YNAB student discount actually a discount, or something better?
- Who qualifies for the YNAB student discount?
- How do you claim the YNAB student discount? (step-by-step)
- What’s the one mistake that blocks the YNAB student discount?
- What do you actually get with the YNAB student discount?
- What does YNAB cost after your student discount year ends?
- How do you set up YNAB as a student?
- How does the YNAB student discount help with financial aid and irregular income?
- What should you watch out for with the YNAB student discount?
- Is the YNAB student discount worth claiming?
- What are the most common questions about the YNAB student discount?
Is the YNAB Student Discount Actually a Discount, or Something Better?
It’s better than a discount. The YNAB student discount gives every currently enrolled college student a full 365-day subscription at $0, not a percentage knocked off the $109 price. Every feature a paying subscriber gets is included from day one, and the only thing you owe YNAB is proof you’re actually in school.
Searching “YNAB student discount” mostly turns up coupon-aggregator sites built for a different kind of deal: a promo code you paste at checkout. That’s not what this is. There’s no code field to fill in and no percentage math to do.
That mismatch is exactly why so many students skim past the offer looking for a discount box that doesn’t exist. YNAB has run this exact program since 2012, well before “student discount” search traffic caught up to what the offer actually is.
The reason it’s this generous comes down to incentives rather than charity. YNAB has said its motivation is building the budgeting habit before graduation, betting that students who use the app for free during school become paying subscribers once they have income to protect. It’s a long-term acquisition play, not charity.
That’s also why the free year isn’t a stripped-down trial version. You get the same zero-based budgeting system covered in the full YNAB review, with nothing held back.
Who Qualifies for the YNAB Student Discount?
Eligibility for the YNAB student discount is broader than most students assume. Any currently enrolled college student qualifies, and YNAB’s own support team has confirmed there’s no narrower definition hiding behind that word. If you’re taking classes anywhere accredited, you’re almost certainly covered.
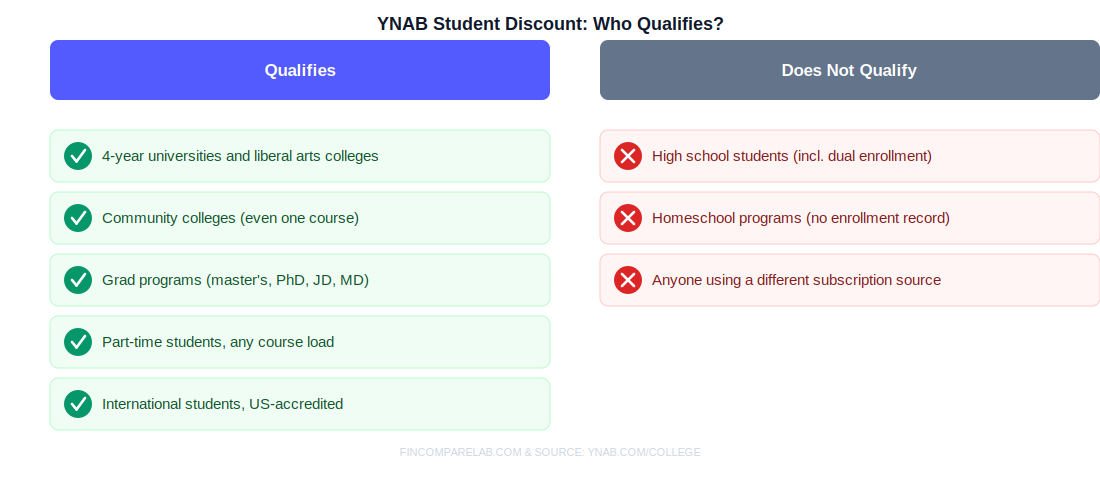
- 4-year universities and liberal arts colleges
- Community colleges, including students taking a single course
- Graduate programs: master’s, PhD, JD, MD, or other professional degrees
- Part-time students, since full-time enrollment isn’t required
- International students at accredited institutions
Two groups explicitly don’t qualify: high school students, even those in dual-enrollment programs, and homeschool programs, since there’s no centralized enrollment record for SheerID to check against. If you’re unsure where you land, the verification step itself will tell you quickly rather than leaving you guessing.
Do Graduate Students and International Students Qualify?
Yes, without exception. YNAB’s own program FAQ puts it plainly: as long as you’re in college, you’re a college student, regardless of degree level or citizenship. Part-time status doesn’t disqualify you either, and international students verify the same way as everyone else once their institution is accredited.
How Do You Claim the YNAB Student Discount? (Step-by-Step)
Claiming the YNAB student discount takes about five minutes once you know where to look. The whole process runs through a dedicated verification partner rather than a coupon field, which is the part that trips people up when they go searching for a promo code instead.
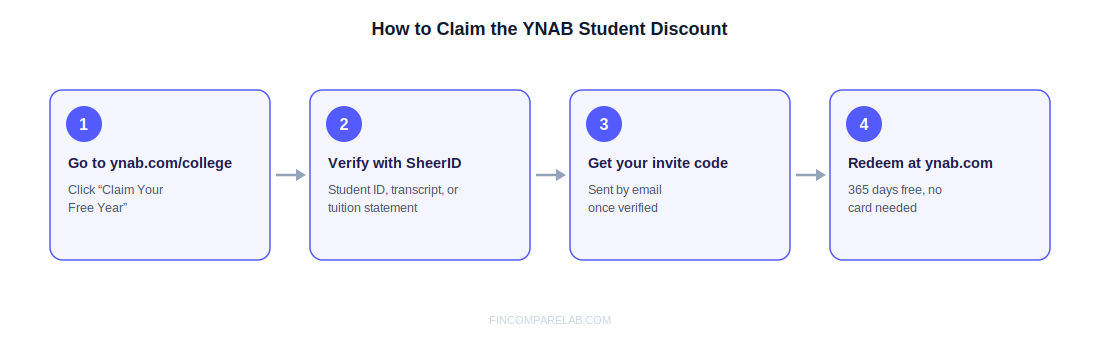
- Go to ynab.com/college directly. Not a search result or a coupon-site link. Go straight to the source and click “Claim Your Free Year.”
- Verify through SheerID. SheerID is YNAB’s enrollment verification partner, the same service Adobe and Spotify use for their own student offers. Submit one document that shows your name, school, and current enrollment date: a student ID card, transcript, or tuition statement all work.
- International students email [email protected] instead. Create your account first, then send proof of enrollment (in English, or with a registrar’s translation attached). Manual review typically takes a few business days.
- Redeem your invite code. Once verified, YNAB emails a unique code. Enter it at ynab.com/college under “Already have a student invite code?” and your free year activates immediately.
What’s the One Mistake That Blocks the YNAB Student Discount?
The single most common mistake with the YNAB student discount has nothing to do with pricing and everything to do with where you signed up. If you subscribed through the Apple App Store first, YNAB can’t apply the college program to that subscription directly, because the college program only runs through YNAB’s own system.
YNAB’s own support page spells out the fix: cancel the App Store subscription (or request a refund through Apple), then email [email protected] with your proof of enrollment so they can set you up manually. Skip that cancellation step and try to redeem your invite code anyway, and it simply won’t apply correctly while an active App Store subscription is running underneath it.
One correction worth flagging here: some older guides, including an earlier version of this one, claimed the App Store also charges a hidden markup on top of YNAB’s direct pricing. That claim doesn’t hold up against YNAB’s live pricing page.
The real $70.88/yr gap you’ll see referenced around YNAB is monthly billing ($14.99 × 12 = $179.88) versus paying annually ($109), and it applies the same way no matter which store you subscribe through. The YNAB pricing guide breaks down that math in full.
What Do You Actually Get With the YNAB Student Discount?
Nothing is held back during your free year. The YNAB student discount includes every feature a $109/yr subscriber pays for, with no watermarked reports or capped bank connections waiting behind an upgrade prompt.
| Feature | Included? |
|---|---|
| Bank sync for US and Canadian accounts | Yes, full access |
| Goal tracking and integrated loan calculator | Yes |
| Reports: spending trends, net worth, age of money | Yes |
| iOS, Android, and web access with full sync | Yes |
| Shared subscription for up to 6 people total | Yes, roommates or partners included |
Features verified from ynab.com/pricing, September 5, 2026.
What Does YNAB Cost After Your Student Discount Year Ends?
Once your YNAB student discount year expires, you’re billed at the standard rate: $109/yr or $14.99/mo, with no automatic charge and no card required to have started. YNAB sends a reminder before the free year ends, so there’s no surprise charge waiting on day 366.
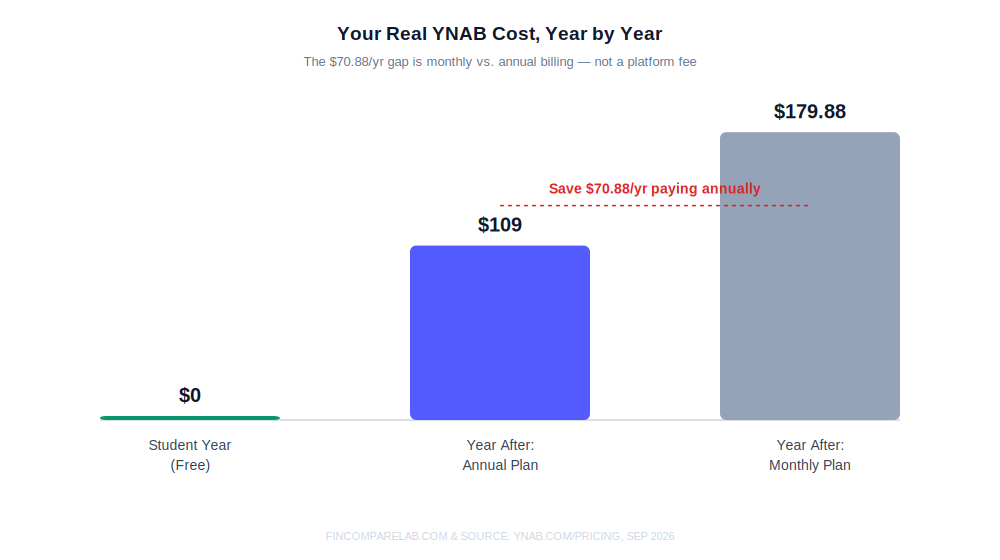
Paying annually at $109/yr works out to $9.08/month, and YNAB’s own pricing page displays that as a “$70 Savings!” badge against the monthly $14.99 rate. That gap is real and worth planning around once the free year runs out.
Set a calendar reminder for the renewal date, and pick annual billing over monthly unless you specifically want the flexibility to cancel month to month. Very few offers in personal finance software match the YNAB student free year for sheer value once you account for that math.
Can You Get a Second Free Year of the YNAB Student Discount?
No. YNAB’s own program FAQ answers this directly: the free year is a one-time offer, full stop, even if you’re still enrolled when it ends. Their stated reasoning is that the app will have already saved you enough money by then that paying for it becomes an easy call rather than a hardship.
How Do You Set Up YNAB as a Student?
Setting up your YNAB student discount account takes about 20 minutes the first time through. The method runs on one rule: give every dollar a job. Whatever’s sitting in your accounts right now gets assigned to a category before you spend it, and “Ready to Assign” should read $0 once you’re done.
What Accounts Should You Connect First?
Start with checking and savings, then add any student loans as tracking accounts so you can see your real net worth, not just your spending. If you carry a credit card, connect that too. YNAB holds the money to cover your balance as you spend on it, which stops you from accidentally double-counting money you’ve already mentally earmarked for the card payment.
Budget only the dollars actually sitting in your accounts, never money you’re expecting. If you’ve got $312 in checking and $50 in savings, assign all $362 to categories today rather than waiting on next week’s paycheck or a pending aid disbursement.
YNAB’s college template, importable at setup, gives you a starting category structure built around dorm costs, textbooks, and the kind of sinking funds a monthly budget usually misses. The YNAB for beginners guide walks through the full setup in more detail if this is your first time using zero-based budgeting.
How Does the YNAB Student Discount Help With Financial Aid and Irregular Income?
Student income rarely looks like a clean biweekly paycheck, and this is where the YNAB student discount earns its keep beyond simple tracking. Work-study hours shift week to week, part-time schedules change by semester, and financial aid tends to land once or twice a year in one large chunk rather than trickling in evenly.
YNAB is built around money you currently have rather than money you expect, so a $4,000 aid disbursement in September gets assigned to tuition, housing, and books immediately instead of sitting in checking looking like spare cash.
Fund each semester’s categories as the money arrives rather than assigning the whole disbursement on day one, since spreading it out prevents the early-semester overspending that catches so many students by surprise. The irregular income budgeting guide covers this pattern in more depth if your income swings widely month to month.
If student loan repayment is approaching, open a dedicated payment category now, even during a grace period, and start funding it before you’re required to pay. YNAB’s loan planner shows the exact interest cost of paying even $25/month extra while you’re still in school, and running your own numbers through the free debt payoff estimator makes the case concrete rather than theoretical.
What Should You Watch Out for With the YNAB Student Discount?
No offer this generous comes with zero friction, and the YNAB student discount is no exception. The learning curve alone catches most first-time users off guard, well before bank sync or renewal timing ever become a concern.
- The learning curve is real, and it isn’t a small one. Every YNAB student hits a wall around week two, when the app’s rules stop making intuitive sense. It tends to click by week three, but that stretch genuinely frustrates people who expected something more passive.
- YNAB expects weekly engagement. If you want an app that quietly tracks spending in the background without a weekly check-in, this isn’t the right fit. Something like a free passive-tracking app suits that use case better.
- Bank sync doesn’t cover every institution. Most major banks and credit unions connect fine, but some smaller credit unions and certain brokerage accounts don’t. You’ll enter those transactions manually, which works but adds a few minutes to your weekly review.
- The free year genuinely doesn’t renew. As covered above, there’s no second free year available even for students who stay enrolled, so build the habit assuming this is your only one.
Is the YNAB Student Discount Worth Claiming?
I used YNAB myself from 2011 through earlier this year, paying full price the entire time, long before any student program like this existed for me. I eventually switched to Monarch Money once my finances got complicated enough to need real net worth and cash flow tracking alongside a budget.
The zero-based habit YNAB taught me in my twenties is the reason I could make that switch as a more advanced user rather than starting from scratch. If I’d had a free year to test it during school instead of waiting, I’d have built that habit years earlier and saved real money doing it.
Claim it if you…
- Are currently enrolled, at any level or course load
- Have student loans now or expect them soon
- Live aid-disbursement to aid-disbursement, not paycheck to paycheck
- Can commit 10–15 minutes a week to a budget check-in
- Share expenses with a roommate or partner
Skip it if you…
- Want fully passive, hands-off tracking
- Won’t realistically open a budgeting app weekly
- Need investment and net worth tracking more than a strict budget
- Bank with an institution outside YNAB’s sync coverage
If the “claim it if” column matches your situation, the only real cost of trying the YNAB student discount is the five minutes it takes to verify enrollment. Start your free year at YNAB →
If it doesn’t, Goodbudget’s free envelope plan is the closest permanently-free alternative, compared directly in YNAB vs Goodbudget. Either way, the best budgeting apps for beginners roundup is worth a look if you’re still deciding between a few options.
What Are the Most Common Questions About the YNAB Student Discount?
A few direct answers to what comes up most before students claim their free year.
Is the YNAB Student Discount Actually Free, Not Just Discounted?
Yes. It’s a full 365-day subscription at $0, not a percentage off the $109 price. Every feature included with a paying account is included here too, with no credit card required to start and no auto-billing once the year ends.
Is the You Need a Budget Student Discount the Same Offer?
Yes. “You Need a Budget” is YNAB’s full company name, so some students search for a you need a budget student discount without realizing it’s the identical program. There’s no separate offer under the full name; it’s the same free 365-day subscription claimed at ynab.com/college.
How Do You Prove You’re a Student for the YNAB Discount?
Submit one document showing your name, school, and current enrollment date, such as a student ID card, transcript, or tuition statement. US students verify instantly through SheerID; international students email [email protected] and allow a few business days for manual review.
Can You Renew the YNAB Student Discount Every Year You’re Enrolled?
No. YNAB’s official position is that the free year is a one-time offer per person, regardless of how long you remain enrolled afterward. Budget for the standard $109/yr rate once your first free year is up.
Is There a YNAB Military Discount Alongside the Student Offer?
No. There’s no separate YNAB military discount for individual service members. ynab.com/wellness is a B2B employer-benefits product sold to organizations, not a personal discount, and it’s unrelated to the student program covered here.
What Happens if You Already Signed Up Through the Apple App Store?
The college program can’t be applied directly to an App Store subscription. Cancel or request a refund through Apple first, then email [email protected] with proof of enrollment so their team can set up your free year manually.
Does the YNAB Student Discount Work Well With Irregular Income Like Financial Aid?
Yes. YNAB only asks you to budget money you currently have rather than money you expect, which fits financial aid disbursements and variable work-study pay better than apps built around a fixed monthly paycheck.
📚 Read Next
- YNAB Review 2026: the full hands-on breakdown behind this program
- YNAB Pricing 2026: every plan, plus the real cost after your free year
- YNAB for Beginners 2026: setting up your first zero-based budget
- YNAB’s 4 Rules Explained: the method behind the app
- Is YNAB Worth It? ROI Calculator: run your own numbers before deciding
- YNAB vs Goodbudget: the closest free alternative after graduation
- Best Budgeting Apps for Beginners 2026: if YNAB doesn’t feel like the right fit
- Best Free Budgeting Apps 2026: no-cost options once your student year ends
- How to Get Out of Debt Fast: tackling student loans after graduation
- How to Budget on Irregular Income: for work-study and aid disbursements
