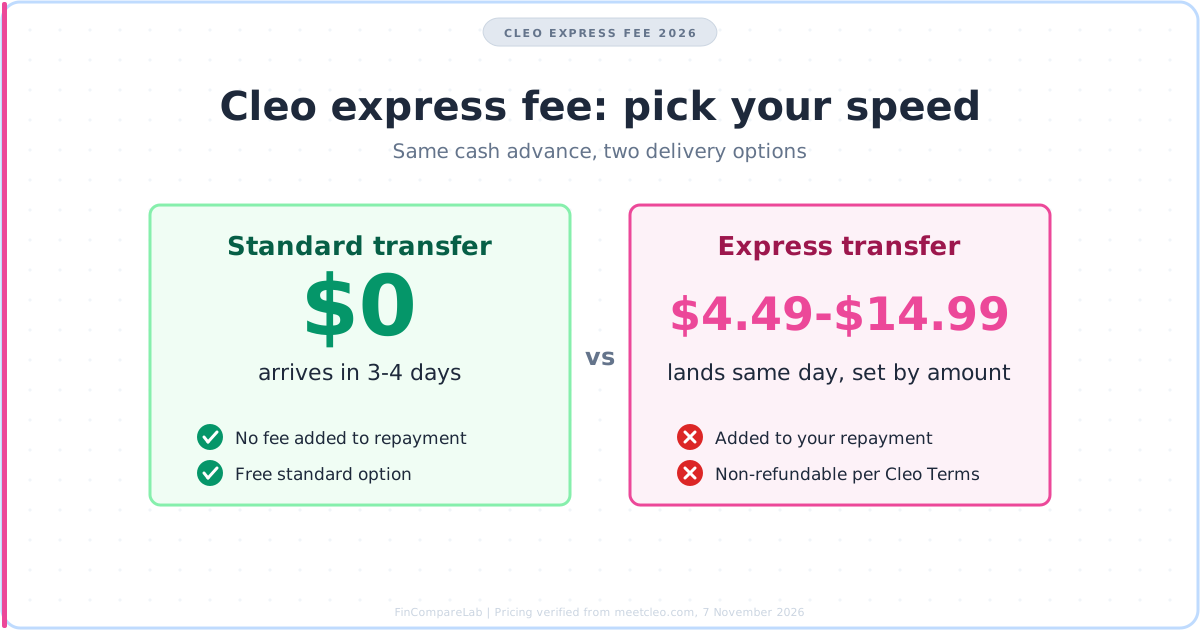
The Cleo express fee is an optional charge of $4.49 to $14.99 that gets a cash advance to you the same day, and Cleo adds it to your repayment instead of taking it up front. Standard delivery is free and takes 3-4 days, so the choice comes down to how soon you need the money.
⚡ Quick Answer
Standard delivery is free and takes 3-4 days. Express costs $4.49 to $14.99, based on the advance amount, and is added to your repayment. Plans run $5.99 (Plus), $8.99 (Pro) and $14.99 (Builder) a month, and Cleo’s Help Center also lists Plus at $44.99 a year.
How We Review Apps, Pricing verified from meetcleo.com — 7 November 2026
What is the Cleo express fee and how much does it cost?
The Cleo express fee is an optional charge of $4.49 to $14.99, set by the advance amount, that delivers a cash advance the same day instead of in 3-4 days. Cleo adds it to your repayment and calls it non-refundable. Standard delivery costs nothing.
Cleo’s pricing page footnotes, its Terms and its Help Center all give the same $4.49 to $14.99 range, and both app store listings now match. Older roundups that still quote $3.99, or a $3.99 to $9.99 range, are out of date.
Cleo doesn’t publish a fee table by advance amount (unconfirmed as of 7 November 2026), so you see your exact figure in the app before you confirm. Standard delivery is loosely defined too. The Terms say an advance generally arrives within three business days, while the Help Center says 3-4 days.
| Delivery | Speed | Cost | When you pay |
|---|---|---|---|
| Standard | 3-4 days | ✅ $0 | Nothing extra at repayment |
| Express | Same day (Terms: within 24 hours) | ⚠️ $4.49-$14.99 | Added to your repayment, non-refundable |
Pricing verified from official websites, November 2026.
The Cleo express fee and your subscription are separate charges. Plus, Pro and Builder bill monthly whether you borrow or not, while the Cleo express fee only appears when you pick same-day delivery. The full Cleo review covers the rest of the app.
When does Cleo take the express fee out of your account?
The Cleo express fee comes out on your repayment date, together with the advance, and you agree to the amount before you confirm the request. A $50 advance with express delivery therefore comes back as one larger debit between 3 and 14 days later, depending on the date you picked.
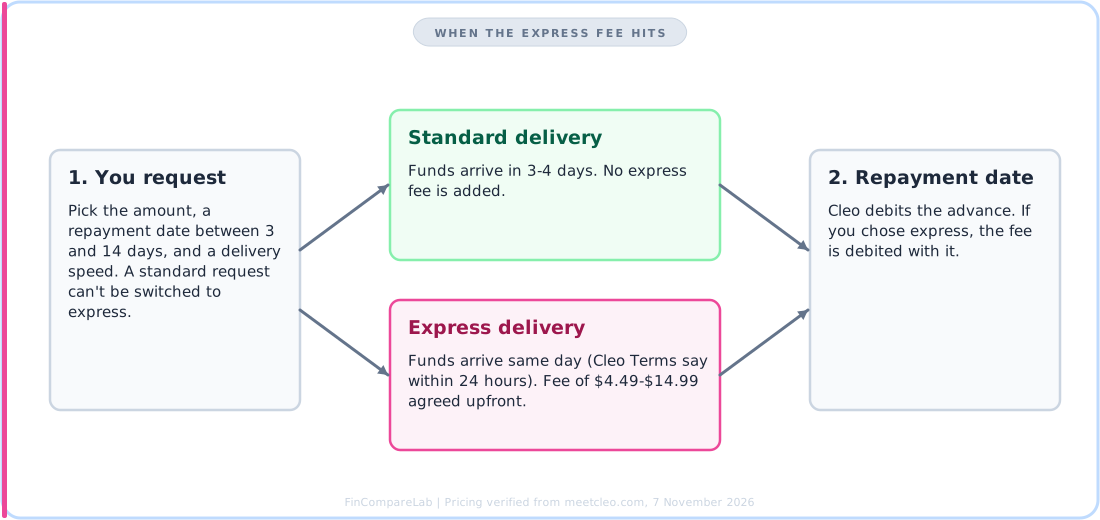
A standard request can’t be switched to express afterward. Processing starts the moment you reach the success screen, so the speed decision happens before you tap confirm. Pick express on the next advance if the first one arrives too slowly.
Timing reads differently across Cleo’s own pages. The pricing page says same day, while the Terms promise funds within 24 hours. If a bill is due at midnight, plan for the money to land the next morning.
The Cleo express fee is non-refundable under the Terms. Whether Cleo returns it when a transfer arrives late isn’t addressed on its pages (unconfirmed as of 7 November 2026).
A short balance on repayment day adds a second problem. Cleo keeps retrying the full amount while your debit authorization stays active, or collects smaller amounts if you opted into Partial Repayments. You can extend the date by up to 7 days through Ask Cleo before the attempt fails, but Cleo doesn’t run manual payment plans.
How much does same-day delivery add to a small advance?
The Cleo express fee floor is $4.49 whatever the advance, so small amounts take the biggest percentage hit. On a $20 first-time advance (Plus and Pro first-timers get $20 to $100), the fee alone is at least 22.5%. Add one month of Plus at $5.99 and that single advance costs at least $10.48, or 52% of the money.
| Advance | Express fee used | Fee alone | Fee plus one Plus month |
|---|---|---|---|
| $20 | $4.49 (floor, minimum) | 22.5% or more | $10.48 or more (52%) |
| $50 | $4.49 (floor, minimum) | 9.0% or more | $10.48 or more (21%) |
| $100 | $4.49 (floor, minimum) | 4.5% or more | $10.48 or more (10.5%) |
| $250 | $14.99 (ceiling, maximum) | 6.0% or less | $20.98 or less (8.4%) |
Pricing verified from official websites, November 2026. Fees by amount are unpublished (unconfirmed as of 7 November 2026), so rows show the published floor or ceiling.
The percentage falls as the advance grows. That makes express easier to justify for a $250 rent shortfall than for $20 of groceries.
Over a year, Cleo costs depend more on the plan you pay for than on any single fee. Four express advances a year is the assumption in the table below.
| Setup | Subscription per year | Year total, 4 express at $4.49 | Year total, 4 express at $14.99 |
|---|---|---|---|
| Plus, billed monthly | $71.88 | $89.84 | $131.84 |
| Plus, annual (Help Center) | $44.99 | $62.95 | $104.95 |
| Builder, billed monthly | $179.88 | $197.84 | $239.84 |
| Customer service route, no plan | $0 | $17.96 | $59.96 |
Pricing verified from official websites, November 2026. Plus at $44.99 a year appears in the Help Center but not on the pricing page, so confirm it in the app.
What does Cleo pricing look like across Plus, Pro and Builder?
Plus is $5.99 a month, Pro is $8.99 and Builder is $14.99 on Cleo’s pricing page, and the free version costs nothing. The Help Center adds that your price depends on when you signed up, with Plus between $1.99 and $5.99 and Builder between $10.99 and $14.99.
| Plan | Monthly | Annual | Advance range | What it adds |
|---|---|---|---|---|
| Free | $0 | n/a | ⚠️ Customer service route only | No fee for Cleo’s money management tools (Terms) |
| Plus | $5.99 | $44.99 (Help Center) | $20-$250, first-time $20-$100 | Cash advance, Equifax credit score, Debt Reset |
| Pro | $8.99 | Monthly only | $20-$250, first-time $20-$100 | Savings at 2.75% APY, advanced AI with voice chat and memory |
| Builder | $14.99 | ⚠️ Conflict: “no annual” vs $134.99 | $150-$500, first-time $150-$180 | Cleo Card, paycheck up to 2 days early |
Pricing verified from official websites, November 2026. Cleo’s Help Center says Builder has no annual option in one article and lists $134.99 a year in another (unresolved as of 7 November 2026).
The Cleo express fee applies on top of every paid plan, so no tier removes it.
Pro costs $3 more than Plus and doesn’t raise the advance ceiling, which stays at $250. You are paying for the savings account and the AI upgrades. The savings rate is 2.75% APY on the pricing page, while the Cleo Pro article says 2.95%, so use the pricing page figure.
Builder adds the Cleo credit builder card and a higher $500 ceiling, so judge that plan on the card’s merits.
For the advance alone, Plus is the plan that makes sense. Anyone who borrows once or twice a year pays $71.88 for twelve months of Plus to use a feature twice. The $44.99 annual price or the customer service route costs less, and the best Cleo alternatives cover apps that charge differently.
Check your own Cleo pricing in the app before you confirm, because your signup date changes the number.
Cleo pricing renews monthly on every paid plan, so Cleo Plus, Pro and Builder all auto-renew. Cancelling Plus means opening Profile, then Subscription, then Unsubscribe, and deleting the app does not cancel anything. Cleo refunds Plus if you cancel within a month of signing up and haven’t requested an advance,, so the refund is gone once you request an advance. The Cleo review covers the sign-up flow in more detail.
What are the Cleo cash advance requirements?
Cleo decides each advance from your paycheck, spending habits and budget, so no checklist guarantees an amount. You need a linked bank account with income Cleo can verify, no advance already outstanding, and at least 24 hours since your last advance was issued.
Meeting the requirements gets you an amount, and the amount sets the Cleo express fee. Plus and Pro advances run $20 to $250, and first-time users get $20 to $100. Builder runs $150 to $500, with $150 to $180 for first-timers, and the $500 tier needs at least $750 a month in direct deposits.
One Help Center article describes a different ladder. Depositing $250 a month unlocks $50 to $200, $500 unlocks $100 to $300, and $750 unlocks $150 to $500. Those ranges don’t match the pricing page, and Cleo hasn’t reconciled them (unconfirmed as of 7 November 2026).
The pricing page footnote also sets a $170 daily disbursement limit for Plus and Pro. One Google Play reviewer says an approved amount arrived in daily pieces, with an express fee on each. Cleo’s pages don’t describe a per-piece fee, so treat that as a user report and read the fee screen on every request.
If the bank connection doesn’t show enough income, the app may ask for a pay stub or documents for benefits, pensions or child support, but only when it prompts you. People on uneven pay can build a buffer first with the guide to budgeting on an irregular income. Speed matters less when the bill has a month of slack.
Is the Cleo credit builder card worth $14.99 a month?
The Cleo credit builder card is a secured credit card that only comes with the $14.99 Builder plan. The card has no separate fee, so its real price is the subscription, or $179.88 over twelve months.
To apply you need to be 18 or older, with a valid SSN and a US address. You fund the Cleo Card with at least $1 of your own money or a cash advance, and that money becomes your security deposit. Borrowing against your next paycheck to fund the deposit only works if you can repay on the date you picked.
How does the Cleo Card report to the credit bureaus?
The Cleo Card reports four items: outstanding balance, payment status, current balance and highest credit. It doesn’t report credit utilization, because Cleo says there is no spending limit beyond the cash you set aside.
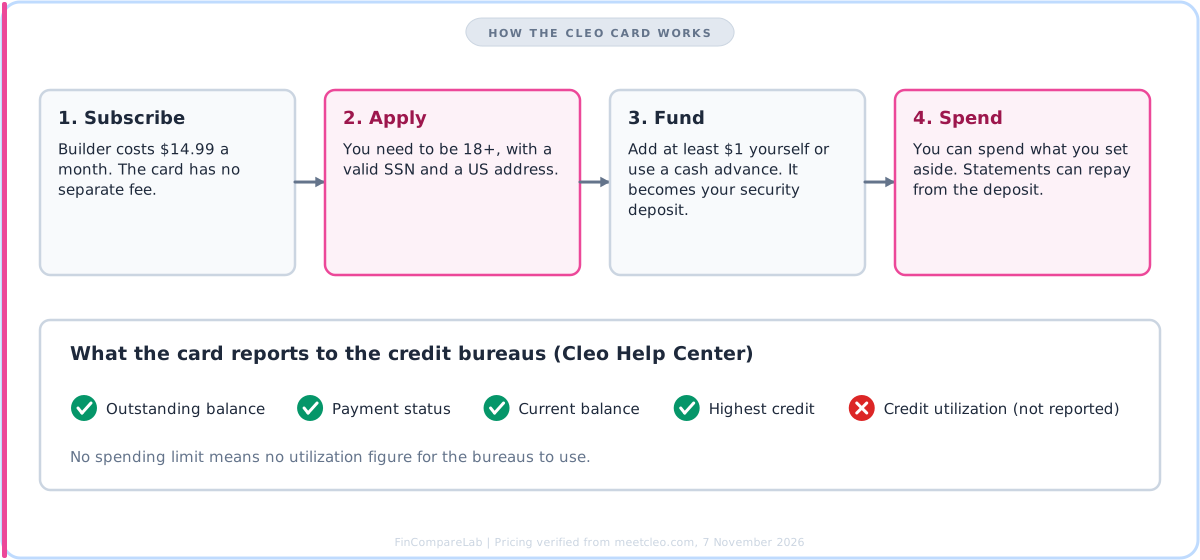
That setup cuts both ways. A thin bank balance is less likely to cause a missed payment, since the money is already set aside. Cleo says the missing utilization figure doesn’t hurt your score, but it also means one score input the bureaus normally see is absent.
Two edge cases matter before you pay. You can’t repay a cash advance with the Cleo Card, because Cleo says to use a debit card or an ACH bank link. Builder refunds within 30 days of signing up don’t apply if you successfully requested the physical card in that window.
Builder costs $179.88 a year before you spend a dollar, so compare it with a secured card whose issuer lists no annual fee. The Cleo credit builder card review covers the card alongside the rest of the app.
How can you skip the fee on a Cleo cash advance?
Skipping the Cleo express fee means choosing standard delivery and requesting early enough that 3-4 days still beats your due date. Start from the decision path below, because the speed can’t be changed after you confirm.
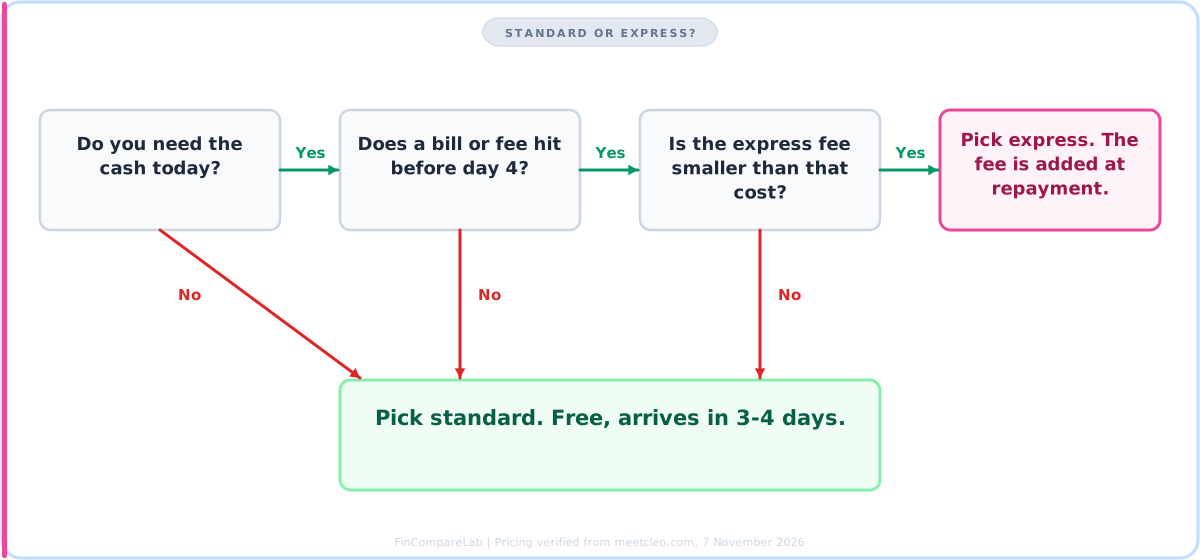
- Request at least four days before the bill is due, so standard delivery lands first.
- Pick a repayment date near your payday, anywhere from 3 to 14 days out, since an extension adds up to 7 more.
- Select standard on the delivery screen, because Cleo can’t switch it to express afterward.
- Open Profile, then Payment help, after the advance lands to see every subscription, express and repayment charge in one list.
If you only need a bridge once in a while, the customer service route skips the monthly plan. The Cleo cash advance requirements stay the same, and subscribing is the simplest way in the app. Weigh that against Albert vs Cleo and the Cleo vs Rocket Money comparison, since both change the cost math.
Cleo Pay Later carries a separate one-time Transaction Fee according to Cleo’s App Store listing. It isn’t the express fee, and the amount is unconfirmed as of 7 November 2026.
Anyone leaning on advances every month is covering a gap that a plan can close. The zero-based budgeting guide and the best budgeting apps for beginners start with giving each paycheck a job before the shortfall shows up.
How does Cleo cost compare with YNAB and Monarch?
Cleo pricing for Plus comes in under YNAB or Monarch Core per year, but the apps do different jobs. Cleo lends against your next paycheck, while YNAB and Monarch plan the money you already have. I paid YNAB’s renewal myself for 15 years, so I weigh any yearly bill against what the app does every month.
| App | Per year | Trial | Main job |
|---|---|---|---|
| Cleo Plus | $44.99 annual or $71.88 monthly | No trial listed on the pricing page | Small cash advances |
| Cleo Builder | $179.88 monthly | No trial listed on the pricing page | Credit building plus advances |
| YNAB | $109 ($9.08 a month) | 34 days, no card | Zero-based budgeting |
| Monarch Core | $99.99 ($8.33 a month) | 7 days, card required | Net worth and cash flow |
Pricing verified from official websites, November 2026.
None of these yearly prices include the Cleo express fee, and Cleo can’t replace a budget. The YNAB pricing guide and the Monarch pricing guide show what those yearly bills include, and the best free budgeting apps cover $0 options. Is YNAB worth it runs the math on your own income.
Did the FTC settle with Cleo over fees and cancellations?
Yes. In March 2025, Cleo agreed to pay $17 million to settle FTC allegations that it misled users about how much money they could get and how fast, and that it made cancelling hard.
The settlement order bars Cleo from misleading consumers about advance amounts and fees. The order covers any fees consumers pay, which includes an optional charge like the Cleo express fee. It also required a simple cancellation method. Cleo settled without an admission, so no court ruled on the allegations.
Law-firm and news write-ups report that the FTC began sending more than $15.8 million to about 2.1 million customers in October 2026, covering people who paid for eligible instant cash advances. The FTC’s own refund page wasn’t read for this update (unconfirmed as of 7 November 2026). The settlement history is also in the Cleo review.
What does the community say about Cleo’s fees?
Community threads and app store reviews repeat four complaints: approved amounts far below $250, a subscription charged before you see your limit, the Cleo express fee stacking on small advances, and cancellations that still bill. Direct Reddit threads weren’t read for this update, so this is the consensus as secondary write-ups report it (unconfirmed as of 7 November 2026).
The same write-ups describe smoother experiences for people who borrow small amounts, choose standard delivery and repay on schedule. That matches the math above, since the express fee hurts most on the smallest advances.
Anyone shopping around can compare apps like Cleo first, and the Rocket Money pricing guide shows how a bill negotiation app charges instead.
What else do people ask about Cleo’s fees and plans?
Does Cleo charge a membership fee?
Cleo’s Terms say there is no fee for using its personal financial management services, so the free version has no Cleo monthly fee. Cash advances sit behind Plus ($5.99), Pro ($8.99) or Builder ($14.99) per month, or the customer service route that skips the plan.
How much does Cleo give you the first time?
Plus and Pro first-time users get $20 to $100, and Builder first-time users get $150 to $180. Cleo bases each amount on your paycheck, spending and budget, and the limit can move up or down later.
Can you get a Cleo cash advance without a subscription?
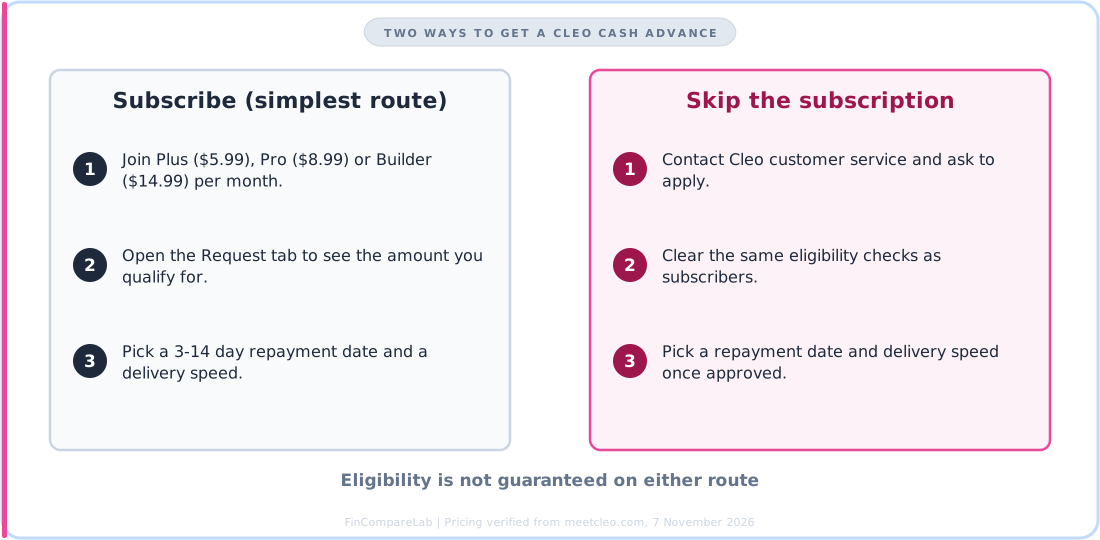
Yes, Cleo’s Help Center says you can apply by contacting customer service and clearing the same Cleo cash advance requirements. Subscribing to Plus, Pro or Builder is the simplest route inside the app.
Does Cleo refund the express charge?
No, Cleo’s Terms call the Cleo express fee non-refundable. Whether Cleo returns it when a transfer arrives late isn’t addressed on its pages (unconfirmed as of 7 November 2026).
Can you switch from standard to express after requesting?
No, Cleo says a standard request can’t be changed to express once you reach the success screen. Choose express on the next advance if you need same-day cash.
Before your next request, read the Cleo express fee on the delivery screen and line up the repayment date with payday. If an advance is part of a bigger debt plan, run it through the debt payoff estimator first, and the guide on how to get out of debt fast covers the order to attack balances.
📚 Read Next
